E-invoicing from 2027: what changes in Slovakia
Act No. 385/2025 Coll. adds mandatory electronic invoicing to the Slovak VAT Act. It does not mean emailing a PDF: an e-invoice is a structured file delivered through a certified provider. Below is who it affects, from when, and what is worth doing before the deadline.
Updated:
Who it affects
- VAT payers
- From 1 January 2027 they must issue e-invoices for domestic supplies to businesses and to legal persons seated in Slovakia, municipalities and public offices included (B2B and B2G). They must receive them too.
- Non-payers of VAT
- They do not have to issue e-invoices in the first phase, but from 1 January 2027 they must be able to receive one from a supplier who is a VAT payer. That includes most živnostníci.
- From 1 July 2030
- The e-invoice becomes the rule for every invoice under the VAT Act, cross-border supplies within the EU included. Simplified invoices, for example, stay an exception.
The deadlines
- 2026
- A preparation year: the delivery service already runs, and a VAT payer may send an e-invoice through it even without the customer's consent. Nothing is mandatory yet.
- 1 January 2027
- VAT payers must invoice domestic supplies to businesses and the public sector with an e-invoice within 15 days of the supply, and report its data to the tax administration. Every business in Slovakia must be able to receive one.
- 1 July 2030
- The e-invoice becomes the rule for every invoice under the VAT Act, cross-border supplies within the EU included.
What an e-invoice actually is
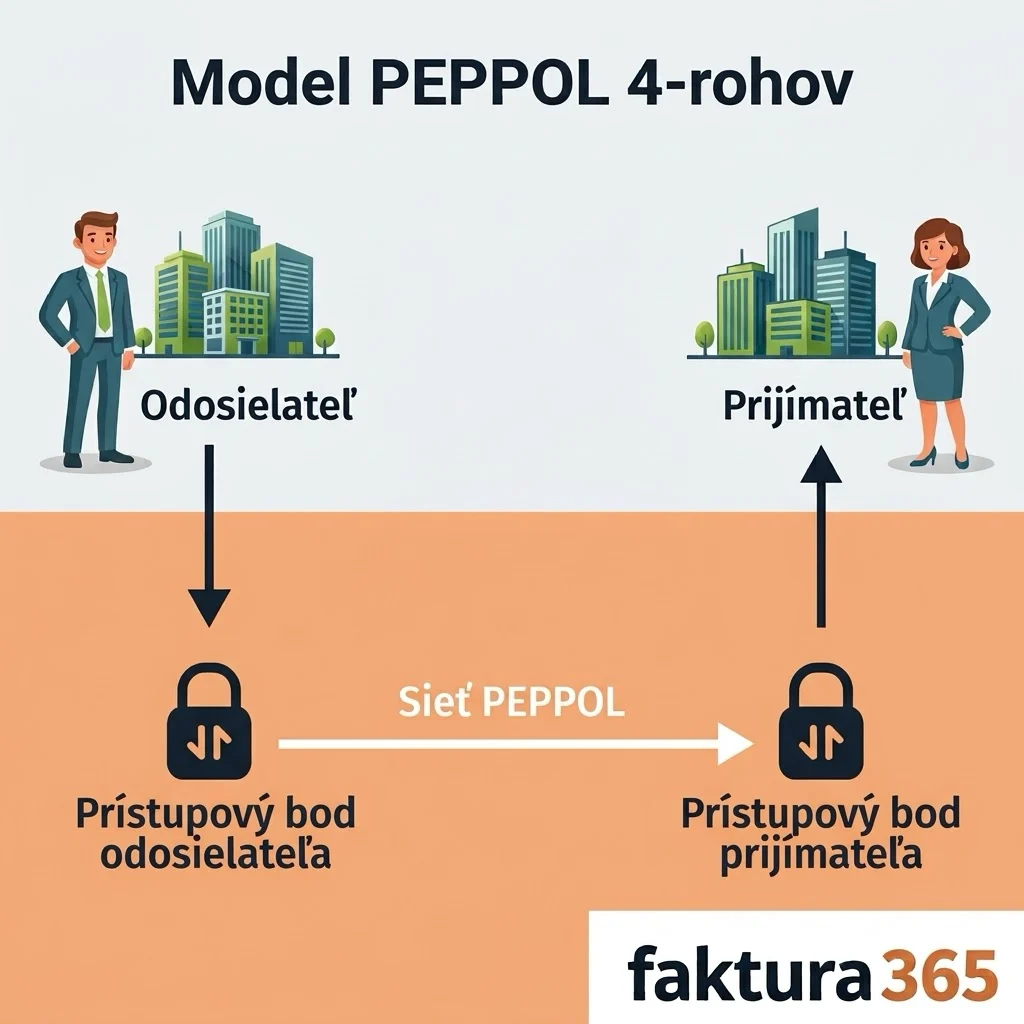
An e-invoice is a structured file — data accounting software reads and posts on its own, not a picture of a document. It does not travel by email: the sender hands it to their certified provider, which delivers it over the Peppol network to the customer's provider, and its data reaches the Finančná správa along the way.
Under the new rules a PDF sent by email is not an e-invoice, however correct its contents.
What to do now
There is nothing to buy in a hurry — the technical details are still being finalised. This is worth doing already:
- Check whether you are a VAT payer under § 4, § 4b or § 4c, or only registered under § 7 or § 7a. That decides whether from 2027 you will also issue e-invoices or only receive them.
- Clean up your customer records. An e-invoice is delivered by DIČ, not by name or email — a typo in the DIČ means the invoice never arrives.
- Ask your accountant how they plan to receive e-invoices, so you do not end up with two programs that cannot talk to each other.
- If you are a VAT payer, try an e-invoice before the deadline. A problem found in December costs less than one found in January 2027.
Frequently asked questions
I am not a VAT payer. Does this affect me at all?
Yes. In the first phase you do not have to issue e-invoices, but from 1 January 2027 you must be able to receive one from a supplier who is a VAT payer. The guide to receiving e-invoices explains how.
Can I keep sending PDFs?
Not for supplies covered by the obligation. A PDF stays perfectly fine for anything outside it — for example an invoice to a private individual.
Does Faktura365 support e-invoicing?
Yes. You can already receive and send e-invoices in Faktura365; the guides below describe how it works. The service is free at least until the end of 2027.
Where do the exact technical rules stand?
Some technical details are still being specified. We keep this page updated — the date above shows when it was last reviewed.
Invoice normally today, and be ready for 2027
Faktura365 keeps your invoices, customers and numbering in one place — the very data an e-invoice is built from.
Open the appSources
This information is general in nature, reflects the state of the rules on the date above, and does not replace tax or legal advice.